1
The network
A PPO network includes participating doctors and hospitals. In-network care can reduce costs, but your provider’s participation and the service’s coverage must both be checked.
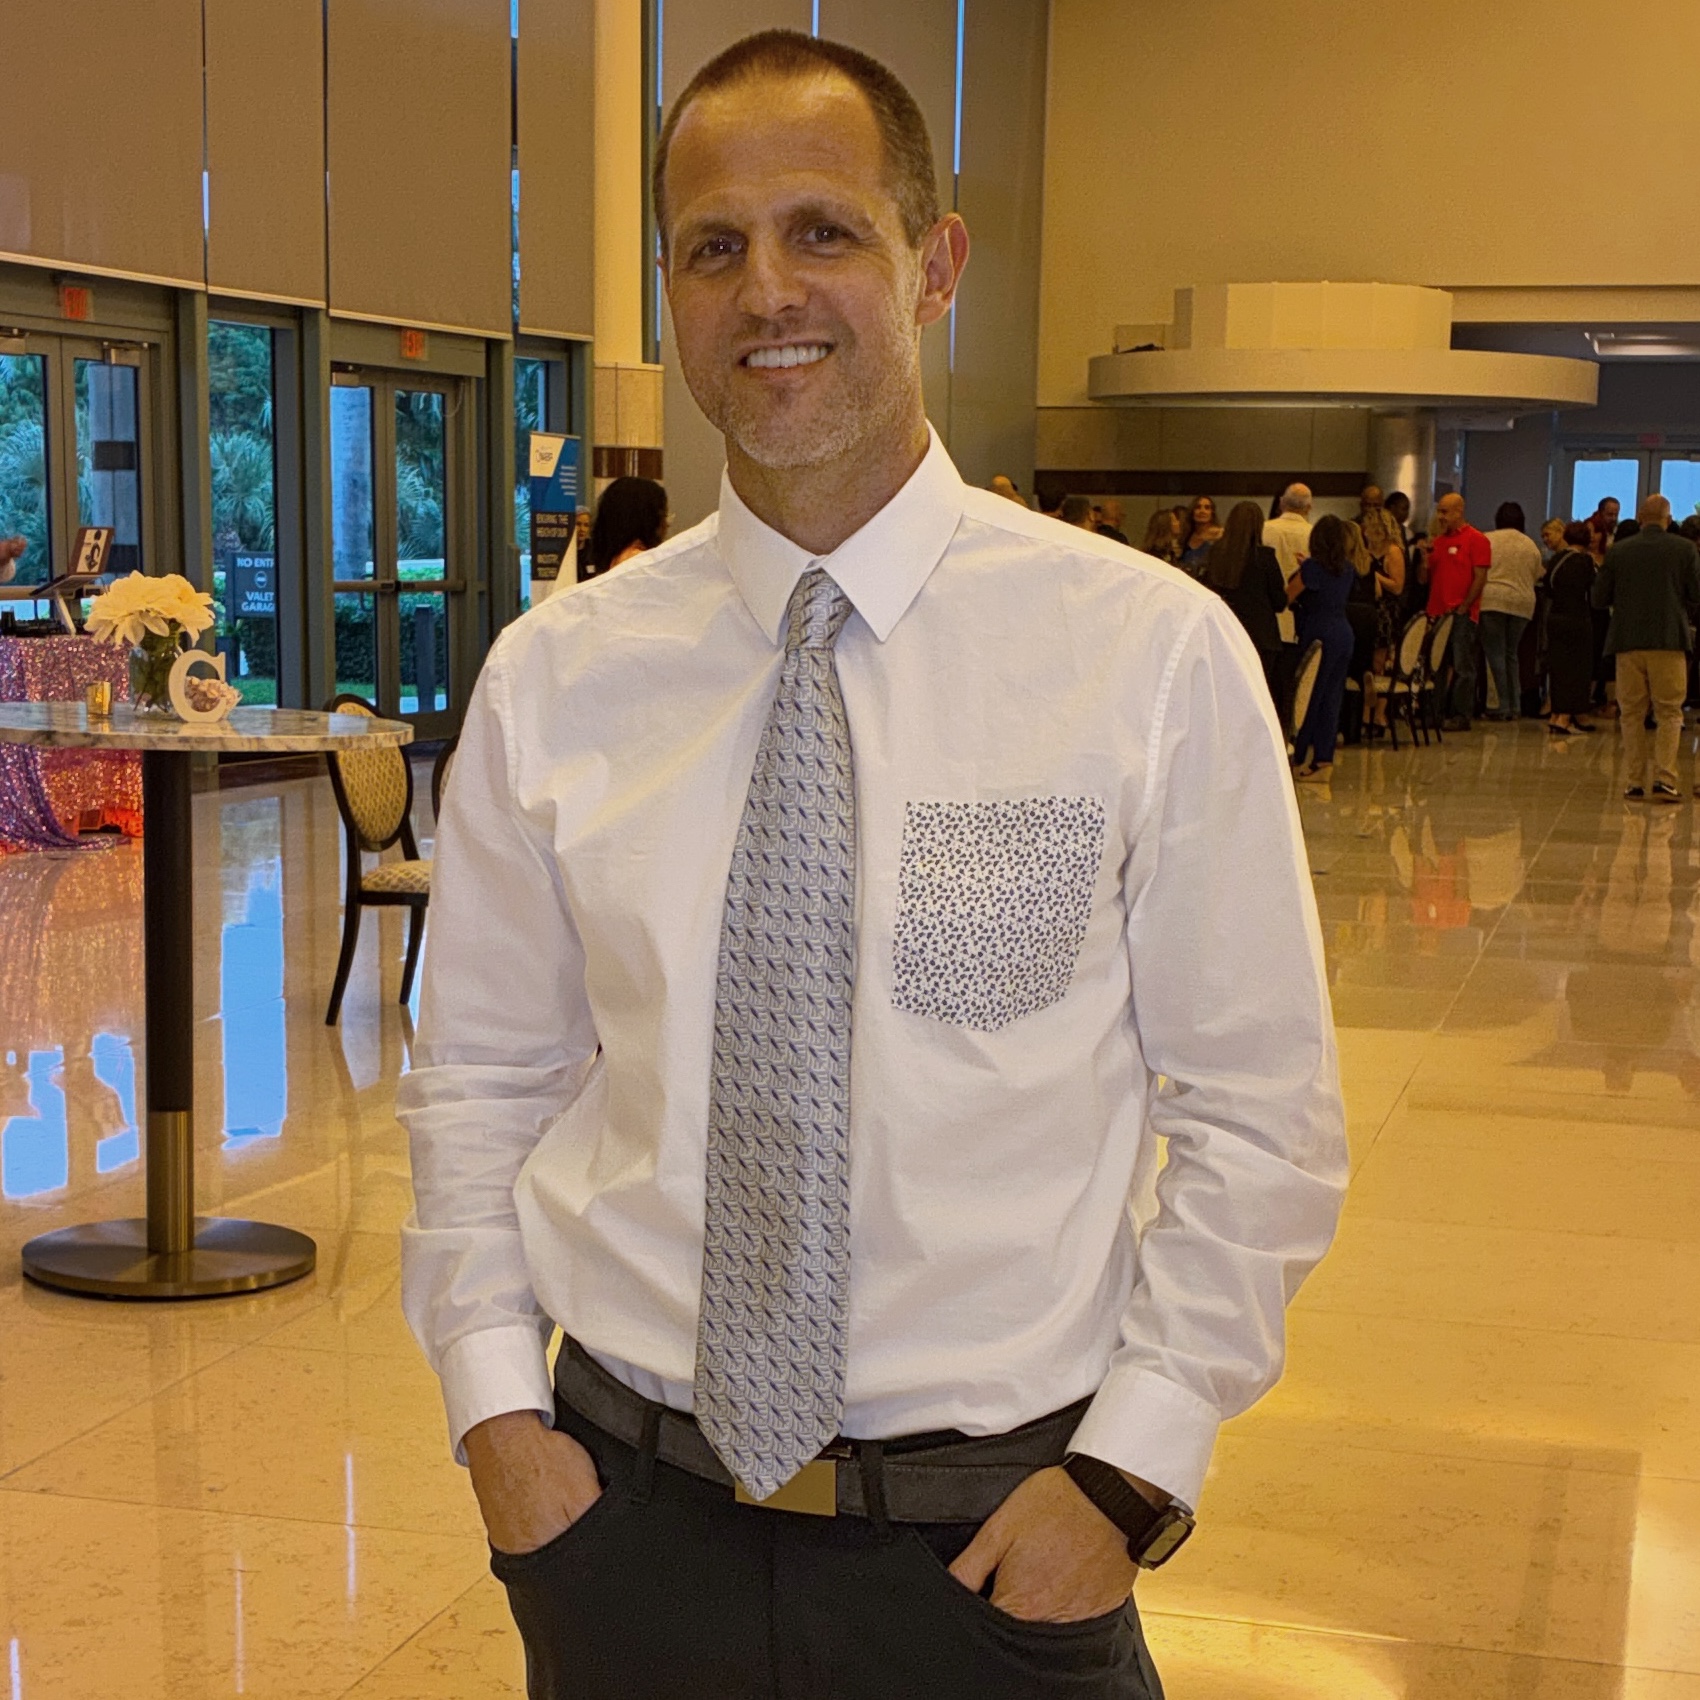
Clear answers. A personal comparison. Eric Jensen helps you understand what’s available—and what a plan would actually cover—before you decide.
Tell Eric a little about the coverage you’re looking for.
No cost, no obligation. Privacy Policy · Terms & Conditions
If you buy your own insurance, work for yourself, or aren’t receiving Marketplace premium assistance, private coverage may be worth comparing.
PPO describes a provider network—not a guarantee of comprehensive coverage. Eligibility and benefits depend on the policy.
Prefer to talk? Call EricHere are the essentials to understand before comparing a plan.
A PPO network includes participating doctors and hospitals. In-network care can reduce costs, but your provider’s participation and the service’s coverage must both be checked.
Private coverage can include different types of insurance. Major medical, short-term, and fixed-benefit policies work differently—even when they offer access to a PPO network.
A lower premium is only part of the picture. Eric helps you compare covered services, your share of costs, benefit limits, health questions, and exclusions.
Some private products use medical underwriting or limit pre-existing conditions. Fixed indemnity policies pay specified benefits and are not a substitute for comprehensive major medical insurance.
Explore my options →You don’t have to sort through unfamiliar insurance terms on your own.
Start with the survey: where you live, who needs coverage, and what you’re looking for.
Eric narrows the available choices and explains the network, benefits, costs, and important limitations.
Ask your specific questions and compare the details. You choose whether to move forward.
The goal is a better understanding of your choices—not a promise that one type of coverage is right for everyone.
Network access does not mean every medical expense is covered. Review the actual policy and benefit schedule before enrolling.
A comparison may be useful if you’re:
Self-employed, between employer plans, or shopping for yourself and your family? Start by checking what’s available.
If you aren’t receiving Marketplace assistance, compare private options alongside comprehensive coverage.
If your current cost, network, or coverage isn’t meeting your needs, Eric can help you understand the tradeoffs.
Marketplace assistance, ongoing health needs, prescriptions, pregnancy, and Medicare or Medicaid eligibility can change which option makes sense. Share those needs with Eric before choosing a policy.
Coast To Coast Health Plans
Get personal help understanding your health insurance options. Eric reviews what’s available for your situation, explains the policy details in plain language, and helps you check the questions that matter to you. The decision stays yours.
Call Eric at (954) 543-1971Straight answers to help you prepare for your conversation.
No. The survey and consultation with Eric are free, with no obligation to enroll. Any insurance premium is separate and will be explained before you decide.
That depends on the specific network and policy. Eric can help check your doctors and hospitals. Confirm participation and coverage for the care you need; a PPO label alone does not guarantee either.
This is a private insurance resource from Coast To Coast Health Plans. It is not a government website or the Marketplace. If you qualify for Marketplace assistance or need ACA protections, those options belong in the comparison too.
Some private products accept applications outside Marketplace Open Enrollment. Availability, effective dates, and eligibility vary by state and product. Eric will confirm the rules for the option you’re considering.
It can. Some private products ask health questions, use medical underwriting, or exclude or limit pre-existing conditions. ACA Marketplace plans have protections for pre-existing conditions. Eric will explain the difference for the actual policy being reviewed.
They depend on the policy. A major medical plan may use deductibles and coinsurance; a fixed-benefit policy may pay a set dollar amount for a covered service, leaving you responsible for remaining charges. Ask to review both the benefit schedule and your possible out-of-pocket costs.
No. A PPO is a provider network arrangement. A policy that uses that network can still have limited benefits, exclusions, or payment caps. Network discounts and insurance payments are different things.
Your information goes to Coast To Coast Health Plans for a follow-up about your coverage needs, consistent with the consent you provide. Eric can review available options and answer your specific questions. Completing the survey is not an application approval or enrollment.
Start with a few details, then get personal answers from Eric Jensen. No cost to compare. No obligation to enroll.
Start my PPO comparison →Prefer a conversation? (954) 543-1971
This is a solicitation of insurance through Coast To Coast Health Plans and licensed insurance agents/producers. This website is not affiliated with or endorsed by any government agency or the Health Insurance Marketplace. Availability, eligibility, benefits, networks, effective dates, and costs vary by state and policy and are subject to the actual policy terms. Some private products are not ACA-compliant major medical insurance and may use medical underwriting, exclude pre-existing conditions, or limit benefits. Fixed indemnity insurance pays specified benefits and is not a substitute for comprehensive health insurance. Not all applicants qualify. This page provides general information, not a quote, approval, or guarantee of coverage. Contact will be consistent with the consent you provide in the survey.
Coast To Coast Health Plans Copyright 2026 -- All Rights Reserved --